

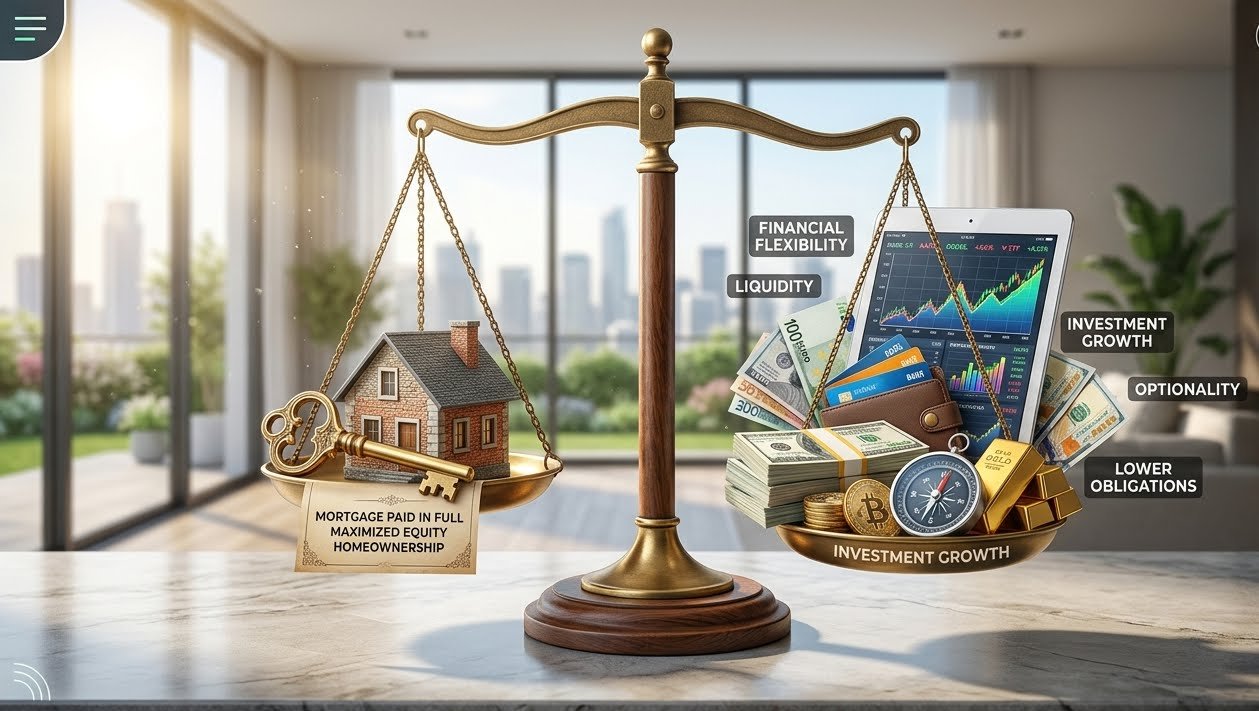
For years, homeowners were encouraged to optimize everything.
Refinance aggressively.
Pay down mortgages early.
Maximize equity.
Leverage low rates.
The logic was straightforward:
The more efficiently you structure your housing finances, the stronger your long-term financial position becomes.
But in today’s economic environment, priorities are shifting.
Increasingly, many households value something else more:
Financial flexibility.
Optimization Works Best in Stable Environments
Traditional housing optimization strategies assume predictability.
Stable income.
Stable rates.
Stable housing markets.
But uncertainty changes decision making.
When economic conditions feel less predictable, households begin prioritizing adaptability over maximum efficiency.
Flexibility Means Optionality
Financial flexibility is the ability to respond to change without major disruption.
It includes:
- Access to liquidity
- Lower fixed obligations
- Strong emergency reserves
- The ability to move or adjust quickly
In uncertain times, optionality itself becomes valuable.
Why Homeowners Are Hesitating to Optimize
Many homeowners are sitting on historically low mortgage rates.
Refinancing or restructuring debt may improve one aspect of their finances but worsen another.
For example:
- A cash out refinance may increase long-term obligations
- Aggressive mortgage payoff may reduce liquidity
- Tapping home equity may weaken future flexibility
Even financially rational decisions can feel riskier when uncertainty is high.
The Shift From Efficiency to Resilience
This is fundamentally a psychological shift.
Consumers are increasingly asking:
“How protected am I if conditions change?”
instead of:
“How optimized is my balance sheet?”
That changes borrowing behavior, savings priorities, and refinancing activity.
Why Liquidity Feels More Important Now
Liquidity provides something optimization often doesn’t:
Breathing room.
In volatile environments, having accessible cash can feel more valuable than minimizing long term interest costs.
That’s why some consumers are choosing to:
- Keep larger cash reserves
- Delay aggressive debt payoff
- Avoid major refinancing moves
The trade off is intentional.
Housing Costs Are Less Predictable
Homeownership itself has become more financially complex.
Beyond mortgages, homeowners now face uncertainty around:
- Insurance costs
- Property taxes
- Maintenance expenses
- Interest rate exposure on HELOCs
This increases the perceived value of flexibility.
Fixed long term obligations feel heavier when surrounding costs are unstable.
Behavioral Economics Explains the Shift
Humans naturally become more risk sensitive during uncertain periods.
Even if optimization offers long term savings, flexibility offers emotional reassurance.
And emotional reassurance strongly influences financial behavior.
That’s why many consumers are choosing “good enough” financial structures instead of aggressively optimized ones.
The Hidden Risk of Over Optimization
Optimizing too aggressively can create fragility.
For example:
- Paying down debt too aggressively may weaken emergency savings
- Leveraging home equity may reduce future mobility
- Stretching to maximize homeownership can increase financial pressure
Efficiency without resilience can become unstable.
The Bigger Picture
This shift reflects broader economic uncertainty.
Consumers are adapting to an environment where:
- Flexibility matters more
- Predictability matters less
- Long-term certainty feels harder to trust
That changes how people think about housing, debt and financial planning overall.
Financial optimization still matters.
But in uncertain markets, flexibility increasingly matters more.
Consumers are no longer asking only how to maximize long term financial efficiency.
They’re asking how to remain adaptable if conditions change.
And in today’s economy, that may be one of the most rational financial shifts happening beneath the surface.

