

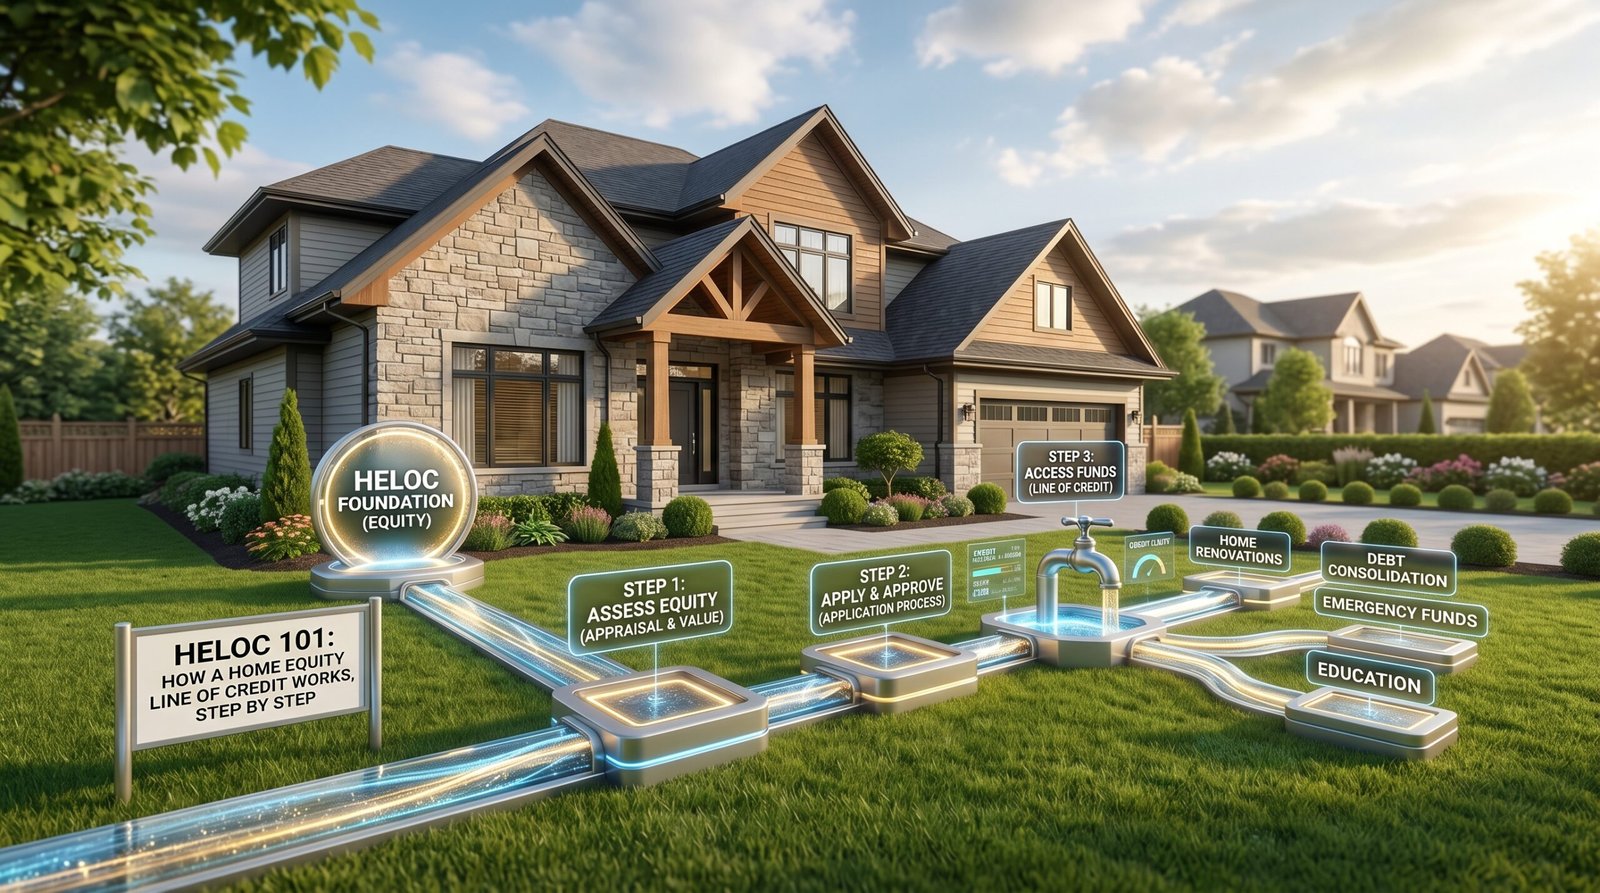
You’ve built equity in your home. A HELOC lets you borrow against it flexibly, repeatedly and at rates well below most alternatives. Here’s exactly how it works.
A home equity line of credit is one of the most versatile borrowing tools available to homeowners and one of the least understood. Most people have a vague sense that it involves borrowing against their home, but the mechanics of how funds are accessed, how repayment works, and what the real risks are often stay fuzzy until after the paperwork is signed.
This guide covers all of it, from the basics to the details that actually matter when you’re deciding whether a HELOC is right for you.
What a HELOC is and what makes it different
A HELOC is a revolving line of credit secured by the equity in your home. Think of it less like a mortgage and more like a credit card except the credit limit is based on your home value, the interest rate is far lower and the stakes are considerably higher.
Unlike a home equity loan, which gives you a lump sum upfront at a fixed rate, a HELOC lets you draw funds as needed, repay them and draw again up to your credit limit, during what’s called the draw period.
That flexibility is the core appeal. You’re not paying interest on money you haven’t used yet and you’re not locked into a fixed repayment schedule from day one.
How equity determines your credit limit
Your available equity is the foundation of the whole transaction. Lenders calculate it like this:
Usable equity = (Home value × LTV limit) − Mortgage balance
Most lenders allow a combined loan-to-value (CLTV) ratio of 80%-90%. That means if your home is worth $400,000 and your lender caps CLTV at 85%, the maximum combined debt they’ll allow is $340,000. If your mortgage balance is $230,000, your maximum HELOC limit would be $110,000.
You won’t always be offered the maximum your credit score, income and debt-to-income ratio all affect the actual limit and rate you’re approved for.
The two phases of a HELOC
Every HELOC has two distinct periods and understanding both is essential before you sign.
The draw period
This is the active borrowing phase typically 5 to 10 years. During this time, you can borrow up to your credit limit, repay, and borrow again as many times as needed. Many HELOCs require interest only payments during the draw period, which keeps monthly costs low but means your principal balance isn’t shrinking.
This is where many borrowers get into trouble: the low payments during the draw period can create a false sense of affordability, only for the repayment phase to arrive as a shock.
The repayment period
Once the draw period ends, the line closes and full principal-plus-interest payments begin typically over 10 to 20 years. On a $60,000 balance at 8.5%, switching from interest only to full repayment can increase your monthly payment by $300-$400 overnight.
Knowing this transition is coming and planning for it is one of the most important things a HELOC borrower can do.
Interest rates: how they work and why they move
HELOCs carry variable interest rates in most cases, tied to a benchmark rate most commonly the U.S. prime rate plus a margin set by the lender.
When the prime rate rises, your HELOC rate rises with it. When it falls, your rate typically falls too, though lenders don’t always pass reductions through immediately.
Rate caps exist on most HELOCs, a lifetime cap (often 18%) and sometimes a periodic cap on how much the rate can move in a given period. Read these terms carefully before signing.
Some lenders offer fixed-rate HELOC options or allow you to lock portions of your balance into a fixed rate. If rate predictability matters to you, these features are worth specifically asking about.
What you can and probably should use a HELOC for
HELOCs work best for expenses that are large, variable, or spread over time. The revolving structure means you only pay interest on what you actually use, which makes it well-suited to:
Home renovations and improvements. The most common use and often the most financially sound one, since improvements can increase the home’s value.
Education costs. Tuition paid in installments over several years fits well within the draw period structure.
Business expenses. For self-employed homeowners with uneven cash flow, a HELOC can serve as a flexible liquidity buffer.
Debt consolidation. Moving high rate unsecured debt to a lower rate HELOC can generate meaningful savings with the important caveat covered in depth elsewhere in this series.
Emergency reserves. Some financial planners recommend establishing a HELOC even if you don’t plan to use it immediately; having the line available provides a low cost safety net that a savings account alone may not cover.
What you should think twice about
Using a HELOC for ongoing living expenses, vacations, or consumption spending is a path that can quietly erode your equity without building anything in return. The low rate makes it tempting. The secured nature of the debt makes the consequences of overextension more serious than a credit card balance.
The fundamental question is whether the thing you’re funding will still be worth something financially or otherwise when you’re still paying for it years later.
The application process, step by step
Step 1: Check your equity and credit. Before approaching lenders, know your home’s approximate current value, your mortgage balance, and your credit score. Most lenders want a score of at least 620; the best rates go to borrowers above 720.
Step 2: Shop at least three lenders. HELOC terms vary more than most borrowers expect. Compare the APR, the margin above prime, rate caps, fees (application, appraisal, annual and early closure fees), and the draw and repayment period lengths.
Step 3: Submit your application. You’ll need proof of income, your mortgage statement, a government ID, and often a home appraisal. Some lenders use automated valuation models (AVMs) instead of a full appraisal, which speeds up the process.
Step 4: Review the disclosure documents carefully. Federal law requires lenders to provide a disclosure document outlining the HELOC’s terms. The variable rate section and the repayment phase payment estimates deserve particular attention.
Step 5: Wait out the rescission period. After signing, federal law gives you three business days to cancel the agreement without penalty. Don’t schedule anything around the funds until that window has passed.
Costs to factor in before you apply
HELOCs are generally lower cost to open than a full mortgage refinance, but they’re not free:
- Appraisal fee: $300-$600 in most markets
- Application or origination fee: $0-$500 depending on the lender
- Annual fee: $50-$100 on many HELOCs
- Early closure fee: Some lenders charge if you close the line within two to three years of opening it worth checking if your plans might change
What happens if your home value drops
If property values decline after you open a HELOC, your lender has the right to reduce or freeze your credit line even if you’ve been making payments on time. This is a contractual right most lenders exercise quietly during housing downturns and it can eliminate access to funds you were counting on.
It’s a scenario worth planning around: don’t structure a multi-year renovation or business plan around HELOC availability if the funds need to be reliably there regardless of market conditions.
HELOC vs home equity loan: the 30-second comparison
| HELOC | Home equity loan | |
| Structure | Revolving credit line | Lump sum |
| Rate type | Usually variable | Usually fixed |
| Payment during draw | Interest only (often) | N/A – repayment starts immediately |
| Best for | Variable, ongoing expenses | One-time, known expense |
| Rate | Slightly lower on average | Slightly higher for rate certainty |
Neither is universally better. The right choice depends on what you’re funding and whether flexibility or predictability matters more.
A HELOC is a powerful borrowing tool for homeowners who understand its two-phase structure, the variability of its rate, and the real consequence of securing debt against their home. Used with clear purpose and honest financial planning, it can fund major expenses at a fraction of what unsecured borrowing would cost.
Used without those guardrails, it can quietly put a home at risk.
Know your draw period end date. Model the repayment phase payment before you sign. And borrow against your equity for things that earn it.
In another related article, The Complete Guide to Debt Consolidation for Households Carrying $20K+

