

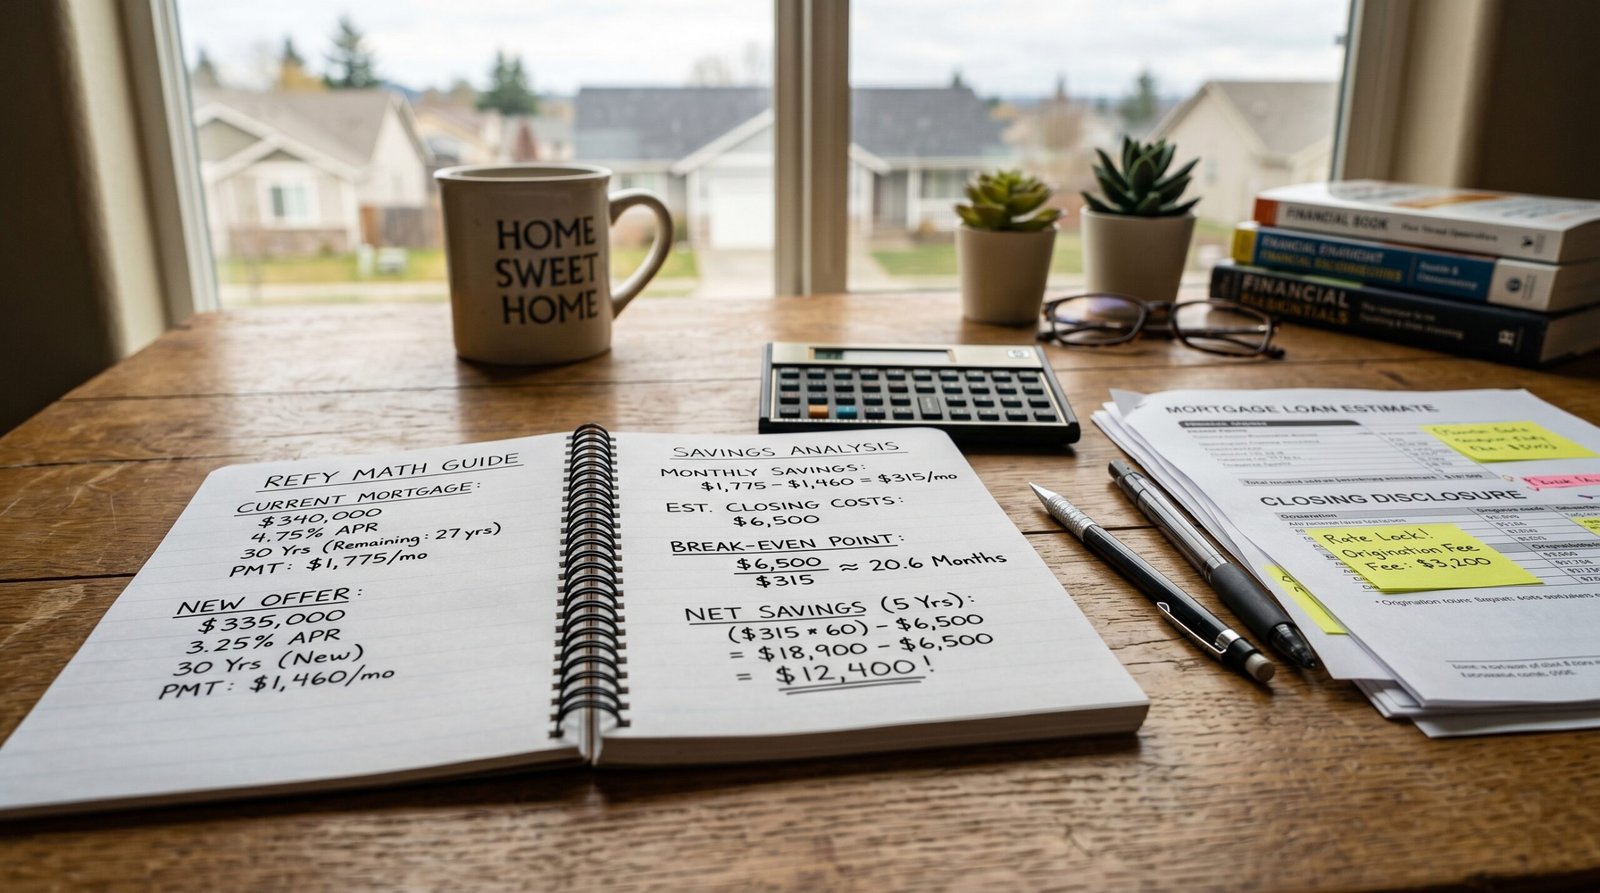
A lower interest rate sounds like a no-brainer but the real question is how long it takes to break even.
Refinancing your mortgage can shave hundreds of dollars off your monthly payment. It can also cost you thousands if you don’t run the numbers first. The difference comes down to one concept most homeowners overlook: the break even point.
Here’s how to figure out whether refinancing actually works in your favor and when it doesn’t.
The break-even point: the only number that really matters
Every refinance comes with closing costs typically 2% to 5% of your loan balance. On a $300,000 mortgage, that’s $6,000 to $15,000 out of pocket (or rolled into your new loan). Your monthly savings need to eventually outpace that upfront cost.
The formula is simple:
Break-even point = Total closing costs ÷ Monthly savings
Say you’re reducing your rate from 7.1% to 6.3% on a $300,000 30-year loan. Your monthly payment drops by roughly $155. If closing costs run $6,200, your break-even point is about 40 months just over three years.
If you plan to stay in the home longer than that, the refinance pays off. If you’re likely to sell or move within three years, you’d lose money.
Four scenarios where refinancing makes financial sense
1. You bought at peak rates and can drop 0.75% or more. The old rule of thumb said wait for a 1% drop. That’s too rigid. Even a 0.5% reduction can pay off quickly if your loan balance is large or your closing costs are low. What actually matters is how fast you break even, not the size of the rate gap alone.
2. You’re switching from an ARM to a fixed rate If you’re on an adjustable rate mortgage and your fixed period is ending, now is the time to model your future payments. A rate adjustment can add $300-$500/month overnight. Locking in a fixed rate offers predictability and in today’s rate environment, that has real financial value.
3. You want to shorten your loan term Refinancing from a 30-year to a 15-year mortgage increases your monthly payment but dramatically reduces total interest paid. On a $250,000 loan at 7%, you’d pay roughly $348,000 in interest over 30 years versus $154,000 over 15. If cash flow allows it, this is one of the highest return financial moves a homeowner can make.
4. You need to access equity and a cash-out refi beats a personal loan If you’re funding a major renovation, consolidating high interest debt or covering a large expense, a cash-out refinance often offers lower rates than personal loans or credit cards. Just be clear-eyed: you’re borrowing against your home and that has consequences if payments become difficult.
When refinancing is the wrong move
- You’re close to paying off your loan. Most of your payment goes to principal in the later years of a mortgage. Refinancing resets that clock and front-loads interest again.
- Your credit score has dropped since you bought. If your score has slipped below 680, you may not qualify for the rates being advertised. Get your credit report before approaching lenders.
- You’re planning to sell within two years. Unless your monthly savings are substantial, you likely won’t reach break-even before you list the property.
- You can’t cover closing costs without rolling them in. Adding costs to your loan balance increases what you owe and reduces your equity which matters if home values dip.
A practical checklist before you call a lender
Before shopping rates, confirm you have:
- Your current loan balance, interest rate, and remaining term
- An estimate of your home’s current market value (try Zillow or Redfin for a rough figure)
- Your most recent credit score (free via most bank apps or Credit Karma)
- A sense of how long you plan to stay in the home
With those four inputs, you can model break-even scenarios yourself or use any free mortgage refinance calculator to stress test a few rate scenarios before committing.
Refinancing works when the math works. A lower rate means nothing if you’re paying $10,000 in closing costs on a loan you’ll exit in 18 months. Run your break even calculation, factor in your timeline, and treat advertised rates skeptically until you know what you’ll actually qualify for.
If the numbers line up, refinancing in today’s environment with rates still elevated but beginning to ease could be a sound long term move for homeowners who plan to stay put.

