For many homeowners, the biggest financial focus has traditionally been the mortgage.
But increasingly, another cost is changing the economics of homeownership:
Insurance.
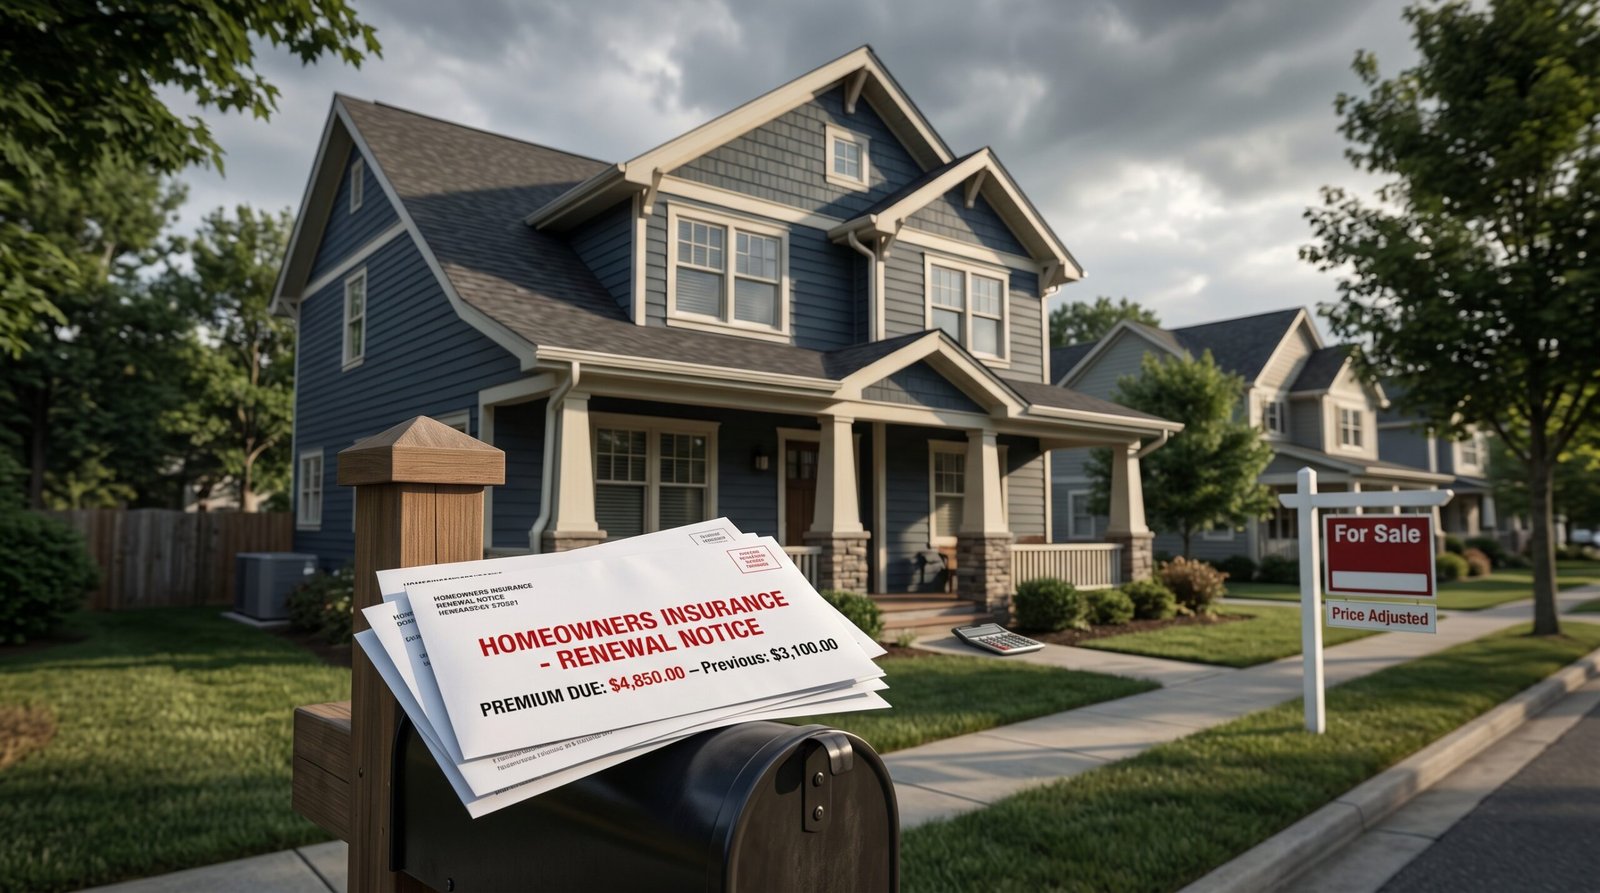
Property insurance premiums have risen sharply across many regions, and the impact extends far beyond monthly budgeting.
Higher insurance costs are quietly reshaping affordability, refinancing behavior, housing decisions and long term financial risk.
Homeownership Costs Are Becoming More Complex
For years, mortgage rates dominated conversations around housing affordability.
Today, the financial structure of homeownership is broader and less predictable.
Beyond principal and interest, homeowners now face increasing pressure from:
- Property insurance
- Taxes
- Maintenance costs
- Climate related risk exposure
Insurance is becoming one of the fastest moving parts of that equation.
Why Insurance Costs Are Rising
Several structural factors are contributing to higher premiums:
- Increased climate-related disasters
- Rising rebuilding costs
- More expensive labor and materials
- Higher property valuations
- Regional risk concentration
As insurers adjust pricing models, homeowners absorb the impact through higher monthly costs.
Rising Premiums Affect Affordability More Than Many Realize
Insurance increases may appear small individually.
But over time, they significantly affect housing affordability.
For many households, rising premiums create:
- Higher escrow payments
- Reduced monthly flexibility
- Increased pressure on fixed budgets
This changes how homeowners evaluate overall housing costs.
Refinancing Calculations Are Changing
Insurance costs also influence refinancing decisions.
Traditionally, homeowners evaluated refinancing based primarily on:
- Interest rates
- Loan terms
- Monthly payment changes
Now, rising insurance premiums complicate those calculations.
Even if refinancing lowers mortgage costs, insurance increases may offset much of the perceived benefit.
That weakens refinancing incentives.
Regional Housing Risk Is Becoming Financially Visible
Insurance pricing increasingly reflects geographic exposure.
That means homeowners in certain regions face growing financial pressure tied to:
- Flood risk
- Wildfire exposure
- Severe weather patterns
This changes long term housing economics in ways many consumers are only beginning to recognize.
Location risk is becoming financially measurable in everyday housing costs.
The Psychological Effect on Homeowners
Higher insurance costs also influence consumer psychology.
When non-mortgage housing expenses rise unpredictably, homeowners feel less financially secure.
That uncertainty can lead to:
- More cautious borrowing behavior
- Delayed refinancing decisions
- Greater focus on liquidity and flexibility
Housing no longer feels like a fixed cost system.
It feels increasingly variable.
Insurance Inflation Changes Long Term Planning
Historically, homeowners often viewed mortgage payoff as the path toward lower housing costs later in life.
But rising insurance and maintenance expenses complicate that assumption.
Even after major debt reduction, ownership costs may continue increasing.
That changes how consumers think about long-term housing stability.
The Broader Economic Impact
If insurance costs continue rising faster than income growth, broader consequences may emerge:
- Reduced affordability in high risk regions
- Lower refinancing activity
- Increased pressure on household budgets
- Greater financial stratification between regions
Insurance is no longer just a background housing expense.
It is becoming a major economic force within the housing market itself.
The Bigger Picture
Homeownership economics are evolving.
The traditional model focused heavily on interest rates and property values.
Now operational ownership costs, especially insurance, are becoming equally important.
That changes both the financial and psychological relationship consumers have with housing.
Rising insurance costs are quietly reshaping homeownership by increasing uncertainty around what it actually costs to own and maintain a home.
And as insurance becomes a larger part of housing affordability, it may influence consumer behavior just as much as mortgage rates themselves.