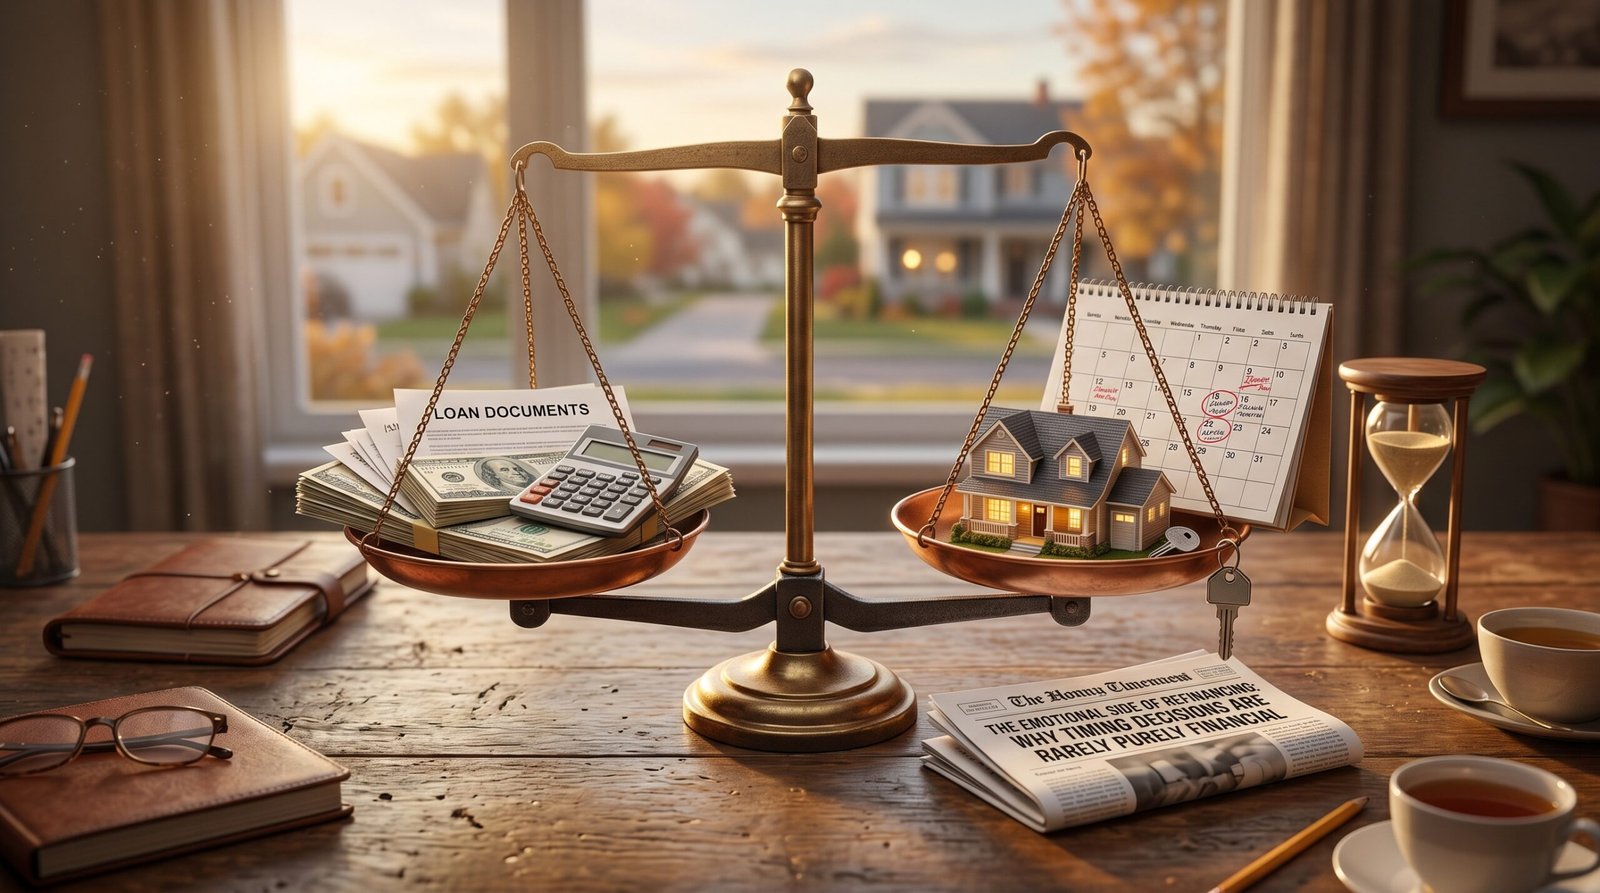
Refinancing is supposed to be a numbers decision.
Compare rates.
Calculate savings.
Choose the best financial outcome.
But in reality, refinancing decisions are rarely driven by math alone.
Emotion plays a much bigger role than most people realize.
Fear, uncertainty, regret, optimism and hesitation all shape how homeowners decide when or whether to refinance.
And in today’s market, those emotional factors are becoming even more influential.
Homeowners Don’t Experience Rates Objectively
Interest rates are not just financial figures.
They are psychological reference points.
A homeowner who locked in a 3% mortgage during previous market conditions may view today’s rates very differently from someone entering the market for the first time.
Even if refinancing still makes financial sense, replacing a historically low rate can feel emotionally painful.
That emotional resistance influences behavior.
The “Wait for Better Rates” Mentality
One of the most common refinancing behaviors is waiting.
Many homeowners hesitate because they believe:
- Rates may fall later
- Better opportunities might appear
- Refinancing now could lead to regret later
This creates a psychological trap.
Consumers delay decisions while searching for the “perfect” moment, a moment that often never arrives.
Fear of Making the Wrong Move
Refinancing changes the long term financial structure.
That naturally creates anxiety.
Homeowners worry about:
- Locking into the wrong rate
- Increasing monthly obligations
- Paying unnecessary fees
- Extending debt timelines
Even when the numbers support refinancing, uncertainty about the future can create decision paralysis.
Loss Aversion Shapes Housing Decisions
Behavioral economics shows that people fear losses more strongly than they value equivalent gains.
That principle heavily affects refinancing.
For example:
A homeowner may reject a refinance opportunity not because it lacks benefits but because it requires giving up an existing low rate mortgage.
The emotional focus becomes the perceived loss, not the potential improvement.
Refinancing Is Tied to Identity and Stability
Housing decisions are deeply personal.
A mortgage is not just debt.
It represents:
- Stability
- Security
- Long-term planning
- Personal success
Changing that structure can feel emotionally significant, even when financially logical.
That’s why refinancing decisions often involve more hesitation than purely mathematical models predict.
Economic Uncertainty Intensifies Emotional Decision Making
Periods of uncertainty increase emotional sensitivity around financial decisions.
When consumers feel uncertain about:
- Employment stability
- Inflation
- Housing prices
- Economic conditions
they become more cautious about restructuring debt.
Even beneficial refinancing opportunities may feel risky in uncertain environments.
Why Some Homeowners Avoid Refinancing Entirely
In some cases, homeowners avoid refinancing simply to preserve familiarity.
Current mortgage structures may not be ideal, but they feel known and predictable.
Refinancing introduces change.
And psychologically, familiarity often feels safer than optimization.
The Cost of Emotional Timing
Waiting too long can carry financial consequences.
Homeowners who delay refinancing decisions may eventually face:
- Higher rates
- Reduced equity access
- Less favorable lending conditions
Ironically, the attempt to avoid regret can sometimes create larger missed opportunities.
This Isn’t Irrational; It’s Human
Financial decisions are never purely mathematical.
People evaluate money through emotion, memory and personal experience.
Refinancing involves uncertainty about the future, and uncertainty naturally activates emotional thinking.
Understanding that reality explains why consumer behavior often differs from what financial models predict.
The Bigger Picture
The emotional side of refinancing reveals something broader about modern financial behavior:
Consumers are not simply optimizing numbers.
They are managing risk perception, stress and psychological comfort at the same time.
That makes financial decisions more complex than spreadsheets alone can explain.
Refinancing decisions are rarely purely financial because homeowners are not just reacting to interest rates.
They are reacting to uncertainty, emotional attachment and fear of future regret.
And in today’s market, psychology may influence refinancing behavior just as much as economics.