

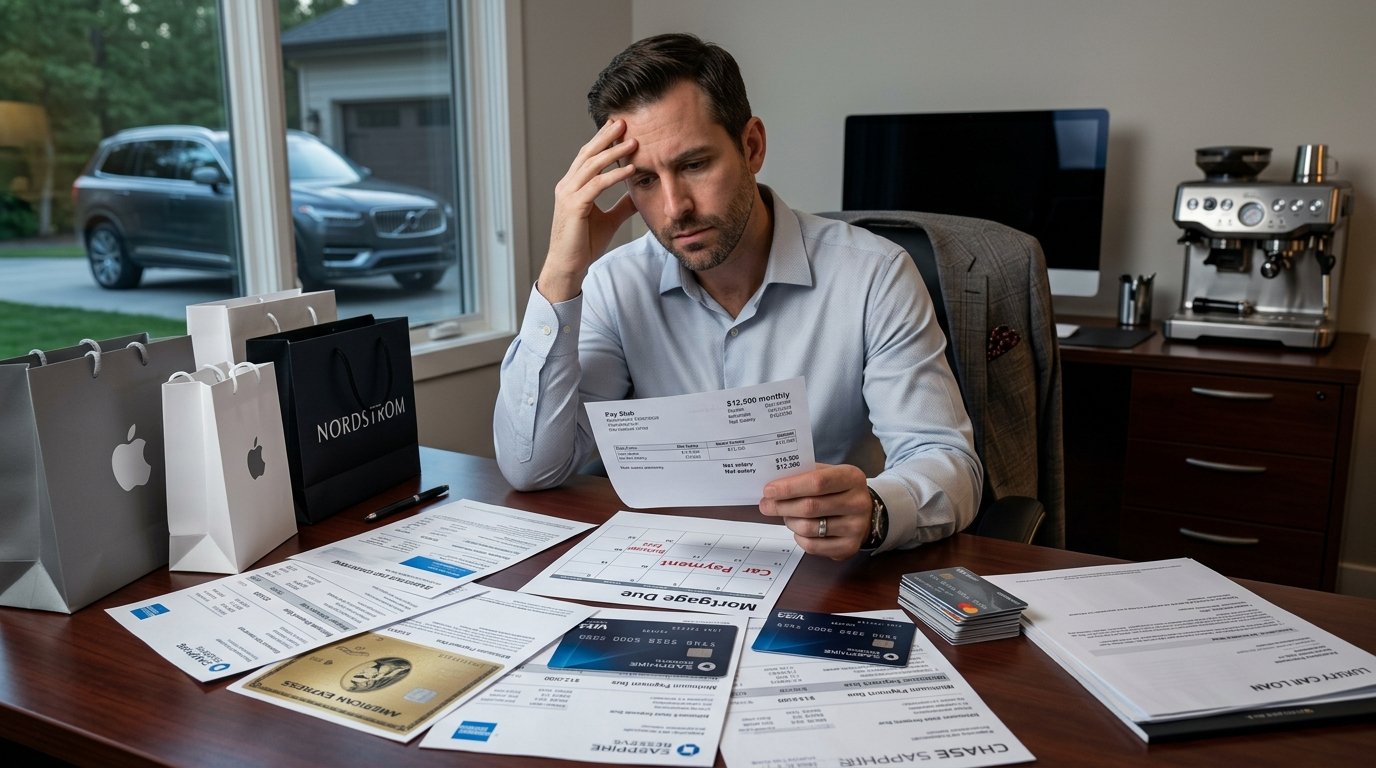
Getting a raise is supposed to change everything.
More income should mean more savings, less debt, and greater financial security.
But for many people, the opposite happens.
Income rises… and so do expenses.
Debt doesn’t shrink, it evolves.
What looks like progress on the surface can quietly become a different kind of financial pressure underneath.
The Expectation vs The Reality
The common assumption is simple:
Earn more → Save more → Owe less
In reality, the pattern often looks like this:
Earn more → Spend more → Borrow more → Stay in the same position
The numbers get bigger.
The lifestyle improves.
But the balance sheet doesn’t strengthen.
That’s the illusion.
Lifestyle Inflation: The Quiet Shift
Lifestyle inflation doesn’t feel dramatic.
It happens in upgrades:
- A better apartment or home
- A newer car
- More dining out
- More subscriptions and services
- Higher expectations for convenience
Each change feels justified.
“I can afford it now.”
And individually, that may be true.
But collectively, these upgrades absorb the income increase and sometimes exceed it.
Why Higher Income Can Lead to More Debt
1. Expanded Borrowing Capacity
As income increases, lenders are willing to extend more credit.
That means:
- Higher credit card limits
- Larger loan approvals
- Bigger mortgages
Access expands alongside income.
And access often leads to usage.
2. Comfort With Higher Payments
When income grows, higher monthly obligations feel manageable.
A $300 payment becomes $500.
Then $800.
The focus shifts from total cost to monthly affordability.
That opens the door to more leverage.
3. Delayed Financial Pressure
Higher income can mask inefficiencies.
If debt is growing but still manageable, there’s no immediate urgency to correct it.
Progress feels real because:
- Bills are paid
- Lifestyle improves
- Stress isn’t immediate
But the underlying structure may not be improving.
The Psychology Behind It
This isn’t just about spending habits. It’s about how people interpret progress.
Income Feels Like Achievement
Earning more feels like forward movement.
That creates a sense of permission:
“I’ve earned this upgrade.”
Spending Feels Like Reward
Higher income often leads to higher expectations for quality of life.
Cutting back can feel like regression even if it’s financially beneficial.
Debt Feels Manageable
As long as payments fit within the budget, debt doesn’t feel dangerous.
It feels controlled.
Until it isn’t.
The Role of Fixed Costs
One of the biggest traps is increasing fixed expenses.
These include:
- Housing
- Car payments
- Insurance
- Recurring services
Fixed costs reduce flexibility.
Once they rise, they’re harder to reverse.
So even if income increases again, much of it is already committed.
That limits the ability to reduce debt.
The Illusion of Stability
From the outside, everything looks better:
- Higher income
- Better lifestyle
- Larger financial footprint
But if:
- Debt is growing
- Savings are stagnant
- Financial flexibility is shrinking
Then progress is more cosmetic than structural.
That’s the illusion.
Why This Pattern Persists
1. Social Comparison
People often adjust their lifestyle based on peers.
As income rises, so does exposure to higher spending norms.
2. Easy Access to Credit
Modern financial systems make it simple to finance upgrades.
The friction is low. The approval is fast.
3. Lack of Clear Benchmarks
There’s no universal standard for “how much debt is too much.”
So as long as things feel manageable, behavior continues.
Breaking the Cycle
Avoiding this trap doesn’t mean avoiding income growth or lifestyle improvement.
It means structuring progress intentionally.
1. Separate Income Growth From Lifestyle Growth
Not every raise needs to translate into higher spending.
2. Prioritize Balance Sheet Improvement
Focus on:
- Reducing total debt
- Increasing net worth
- Building liquidity
Not just increasing income.
3. Control Fixed Costs
Keep major obligations aligned with long term flexibility.
4. Use Raises Strategically
Allocate increases toward:
- Debt reduction
- Savings
- Investments
Before expanding lifestyle.
The Bigger Picture
Higher income creates opportunity.
But it doesn’t guarantee progress.
Without structure, it can simply support a more expensive version of the same financial position.
True progress isn’t about how much you earn.
It’s about what your financial position looks like after you earn it.
Earning more should make life easier.
But without intentional decisions, it can also make financial structures more complex and more leveraged.
The illusion of progress comes from focusing on income instead of outcomes.
Because real progress isn’t measured by how much money flows in.
It’s measured by how much control you have over where it goes.

