

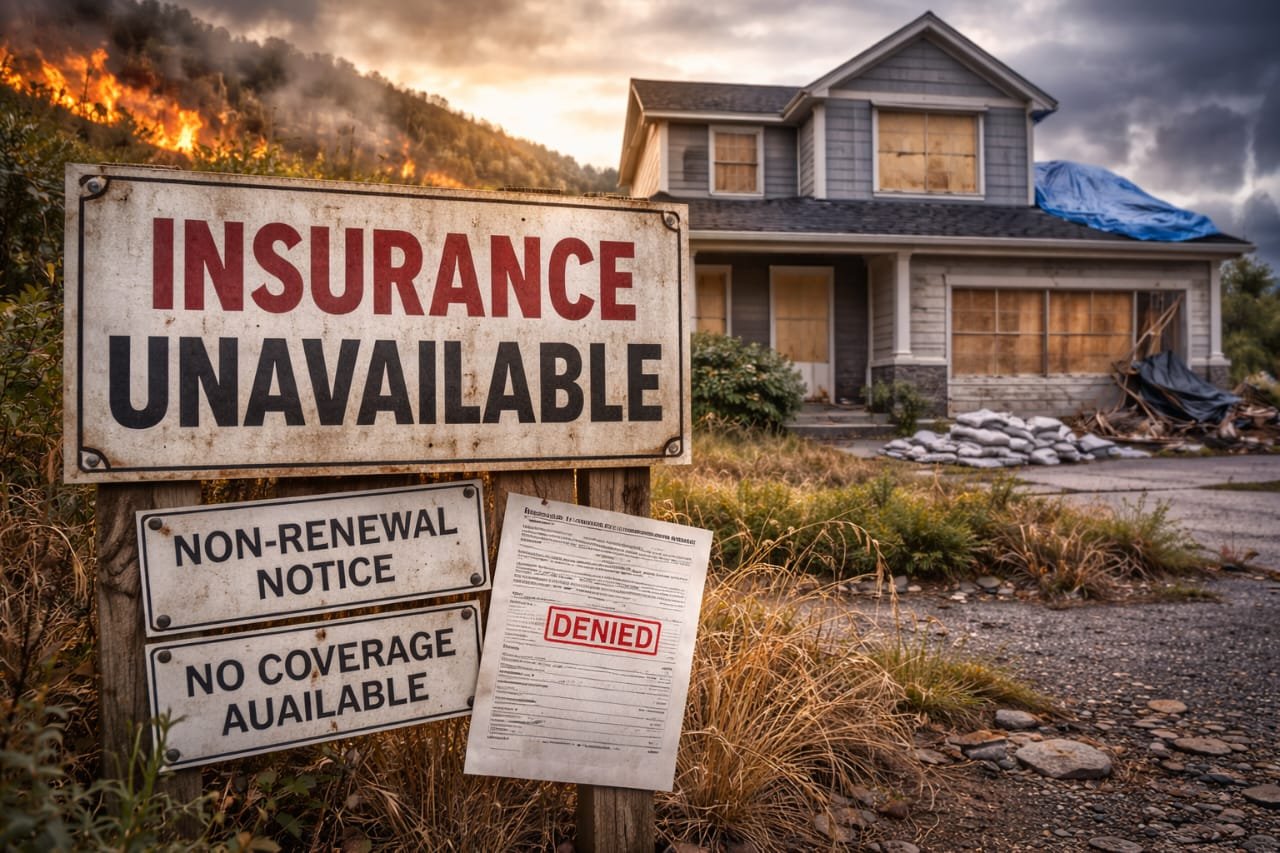
In parts of the United States, insurance is not just getting more expensive. It is quietly becoming harder to find at all.
The term “insurance desert” is increasingly used to describe areas where private insurers have reduced coverage, stopped writing new policies, or exited entirely. Unlike headline grabbing rate hikes, these changes often happen gradually. A non renewal notice arrives. A broker says no carriers are quoting. Options narrow.
For homeowners and small businesses, availability can matter more than price.
How Markets Become Insurance Deserts
Insurance deserts rarely form overnight. They typically emerge from a combination of rising claims, concentrated risk, and mounting losses.
According to data tracked by the National Association of Insurance Commissioners, catastrophe related losses have increased in frequency and severity over the past decade. In wildfire-prone parts of the West and hurricane-exposed coastal states, insurers have reported sustained underwriting losses.
When losses persist, companies adjust in three ways:
- Raise premiums
- Tighten underwriting standards
- Reduce geographic exposure
It is the third step that creates deserts.
In some high risk counties, insurers decline new business entirely. Existing customers may face non renewals if properties no longer fit updated risk models.
The Geography of Withdrawal
Insurance deserts are most visible in catastrophe exposed regions. Coastal areas vulnerable to hurricanes, wildfire corridors, and certain floodplains have seen the sharpest pullbacks.
But the phenomenon is not limited to climate risk. Urban neighborhoods with elevated crime rates have experienced reduced availability of certain commercial or property policies. In rural areas, sparse populations and limited repair infrastructure can make underwriting less attractive.
What unites these areas is actuarial concentration of risk. Modern modeling tools allow insurers to measure exposure down to individual parcels. That precision can lead to strategic retreat.
The Role of Reinsurance
Behind the scenes, reinsurance markets play a critical role. When global reinsurers increase prices or restrict coverage following major disasters, primary insurers face higher capital costs. Those pressures cascade down to local markets.
In recent renewal cycles, reinsurance pricing has risen sharply in catastrophe heavy regions. For some carriers, withdrawing from the riskiest ZIP codes becomes a rational balance-sheet decision.
State Backed Insurers as a Backstop
When private carriers step back, state sponsored insurance pools often expand. These programs, sometimes referred to as insurers of last resort, provide coverage to homeowners who cannot secure private policies.
However, such policies can carry higher premiums, narrower coverage, or larger deductibles. Concentrating high risk properties within public pools can also create long-term fiscal concerns for states.
The existence of a backstop does not eliminate the structural issue. It merely redistributes it.
Housing Markets and Financial Spillover
Insurance availability directly affects property values and mortgage access. Lenders require homeowners insurance as a condition of financing. If coverage becomes scarce or prohibitively expensive, transaction activity can slow.
In this way, insurance deserts are not just an industry problem. They intersect with housing affordability, municipal tax bases, and local economic stability.
A Quiet Structural Shift
Insurance has historically functioned as invisible infrastructure. It operates in the background, enabling homeownership, business formation, and credit expansion.
The emergence of insurance deserts signals a structural recalibration of risk. As climate volatility increases and modeling grows more granular, geographic differentiation intensifies.
For households and investors alike, the implication is straightforward. Availability risk is becoming as important as premium risk.
In certain markets, the central question is no longer “How much will this cost?” but “Will this be offered at all?”
In another related article, The Geography of Risk: Why Where You Live Matters More Than Ever for Insurance

