

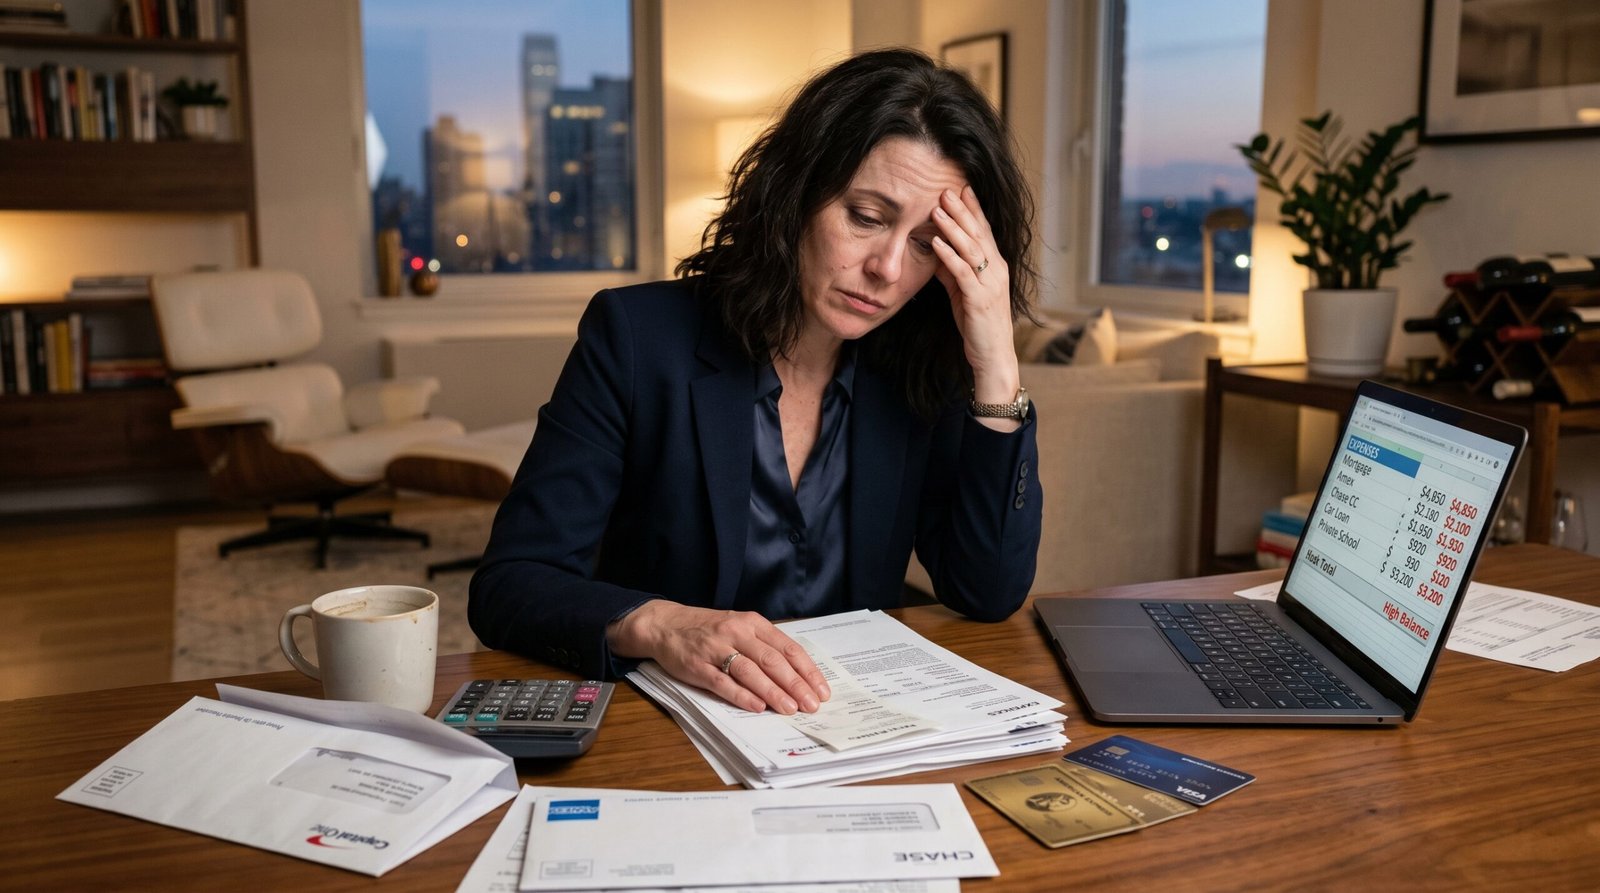
For decades, higher income was viewed as the solution to financial stress.
Earn more money, and stability follows.
But increasingly, many middle and upper middle income households are discovering something uncomfortable:
Higher income no longer guarantees financial security.
In some cases, it simply supports a more expensive version of financial pressure.
The Modern Debt Trap Looks Different
Traditional debt distress was often associated with low income.
Today, the picture is more complex.
Many higher earners still carry:
- Large mortgage obligations
- High car payments
- Credit card balances
- Student loans
- Home equity debt
On paper, these households appear financially strong.
In reality, many operate with thin flexibility.
Income Growth Expanded Spending Capacity
As income rises, borrowing capacity rises too.
Lenders become more willing to extend:
- Larger mortgages
- Higher credit limits
- Bigger financing packages
That creates a subtle trap.
Instead of improving balance sheets, higher income often expands lifestyle expectations and fixed obligations.
The result is leverage scaling alongside earnings.
Lifestyle Inflation Is Structural
Lifestyle inflation isn’t always reckless.
It often happens gradually:
- Better neighborhoods
- More expensive childcare
- Private education
- Larger homes
- Higher insurance costs
As income grows, these expenses begin to feel “normal.”
But once fixed costs rise, financial flexibility shrinks.
Why Higher Earners Still Feel Financial Pressure
Many middle class households experience a contradiction:
Income is high.
Stress is still high.
That’s because financial security depends less on income alone and more on the gap between obligations and flexibility.
A household earning more but carrying:
- High fixed expenses
- Significant debt obligations
- Minimal liquidity
may feel less secure than a lower income household with fewer obligations.
Debt Is Quietly Supporting Lifestyle Stability
In many cases, credit has become part of maintaining middle class living standards.
Not necessarily for luxury spending.
But for sustaining:
- Housing expectations
- Consumption patterns
- Family obligations
- Everyday convenience
This creates a financial structure where income alone no longer supports lifestyle.
Income plus leverage does.
The Psychological Pressure of “Keeping Up”
Social comparison amplifies the problem.
Higher-income households are often surrounded by peers with similar or greater spending patterns.
That environment resets expectations.
What once felt luxurious becomes standard.
And because many expenses are financed rather than paid outright, the true cost can feel less immediate.
High Income Can Hide Structural Weakness
One reason this issue remains overlooked is because higher income masks financial vulnerability.
As long as:
- Payments are manageable
- Credit remains available
- Income stays stable
the system appears sustainable.
But stability built on leverage depends heavily on continued earnings.
When disruption occurs, pressure rises quickly.
Why This Matters Long Term
If higher earners increasingly depend on debt to maintain lifestyle stability, long term consequences may include:
- Reduced savings rates
- Delayed retirement preparedness
- Increased sensitivity to economic downturns
- Greater financial anxiety despite rising income
This changes the traditional relationship between earnings and security.
The Bigger Picture
The modern debt trap is not always about overspending.
It’s often about structural adaptation.
As living costs rise and social expectations shift, debt becomes integrated into maintaining middle class life.
The issue is not simply how much people earn.
It’s how dependent financial stability becomes on continued access to leverage.
Higher income still creates opportunity.
But it no longer guarantees resilience.
Without flexibility, liquidity, and controlled obligations, higher earnings can support the appearance of stability while masking growing financial exposure underneath.
And that may be the defining characteristic of the modern middle class debt trap.

