

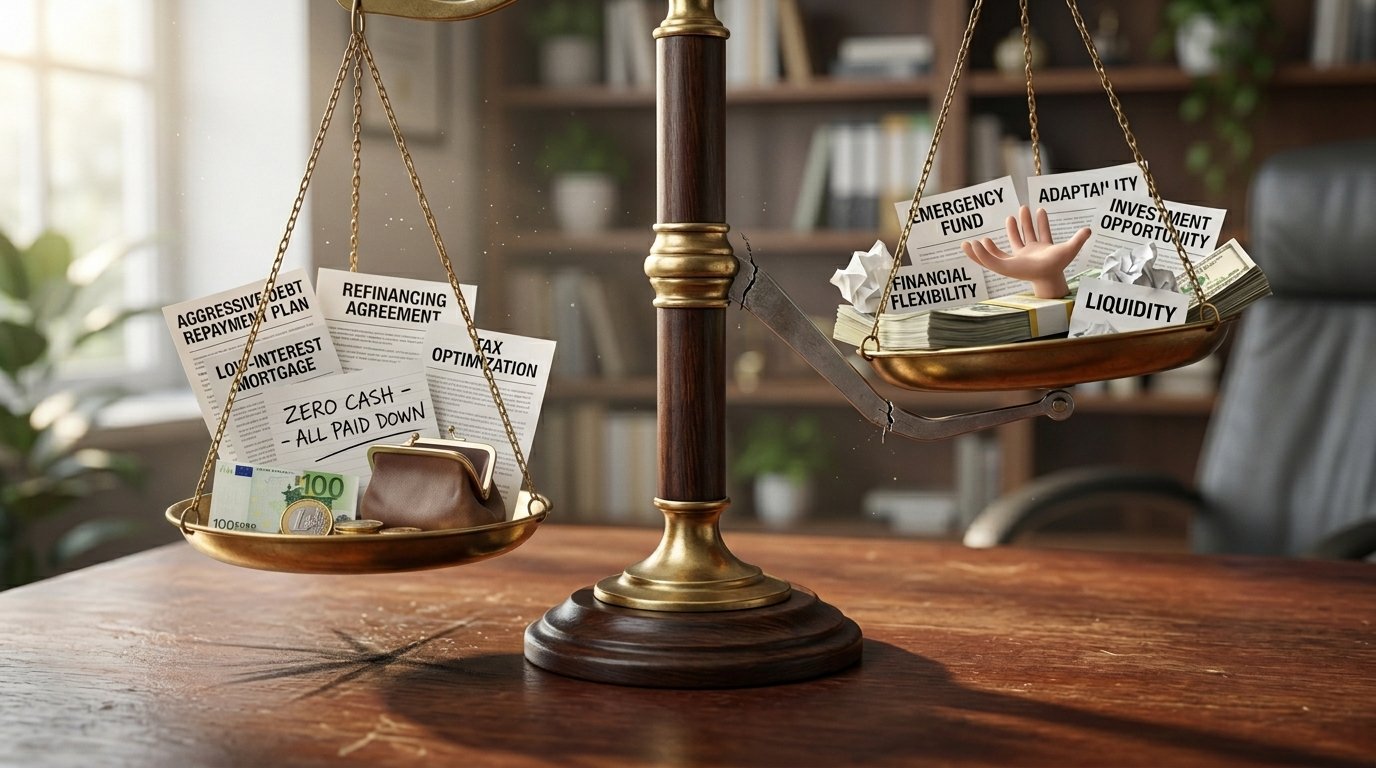
In personal finance the “best” move is usually defined by math.
Lower the interest rate.
Pay off debt faster.
Reduce total cost over time.
On paper that’s optimal.
In real life it’s not always that simple.
Because optimizing too aggressively can quietly reduce something just as important:
financial flexibility.
What Debt Optimization Gets Right
Let’s start with the obvious.
Debt optimization works.
- Paying extra toward high interest balances saves money
- Refinancing into lower rates reduces long-term cost
- Consolidating debt simplifies repayment
From a purely mathematical perspective, these are rational, effective strategies.
But math assumes stability.
Life doesn’t.
What Flexibility Actually Means
Financial flexibility is your ability to absorb change without stress.
It includes:
- Access to cash
- Low fixed obligations
- Room in your budget
- The ability to adapt to unexpected events
Flexibility is what allows you to handle:
- Job loss
- Income drops
- Medical expenses
- Market shifts
Without it, even a well optimized financial plan can break under pressure.
Where the Trade Off Begins
The trade-off shows up when optimization reduces optionality.
1: Aggressive Debt Payoff
Putting every extra dollar toward debt can feel like progress.
But if it leaves you with:
- Minimal emergency savings
- No liquidity buffer
You’ve traded long-term efficiency for short term vulnerability.
If an unexpected expense hits, you may need to borrow again, often at worse terms.
2: Cash Out Refinancing
Refinancing to consolidate high-interest debt into a lower-rate mortgage can improve cash flow.
But it can also:
- Increase total loan size
- Extend repayment timelines
- Tie more of your financial life to your home
You reduce interest cost but increase structural exposure.
3: Locking Into Long Term Loans
Choosing the lowest possible rate often means accepting longer terms or stricter structures.
That can reduce:
- Prepayment flexibility
- Mobility
- Future refinancing options
Optimization can quietly limit future choices.
Why This Trade Off Gets Ignored
1. Math Feels Certain
Saving $10,000 in interest is easy to quantify.
The value of flexibility is harder to measure.
It only becomes visible when something goes wrong.
2. Short Term Wins Are Visible
Lower payments. Smaller balances. Clear progress.
These are immediate and rewarding.
Flexibility, on the other hand, feels like “unused potential.”
Until it’s needed.
3. Financial Advice Often Prioritizes Efficiency
Most guidance focuses on minimizing cost.
Less attention is given to maintaining resilience.
But efficiency without resilience can be fragile.
The Risk of Over Optimization
When financial decisions are pushed to their logical extreme, risk increases.
Over-optimization can lead to:
- Thin cash reserves
- High dependence on stable income
- Limited access to liquidity
- Increased exposure to fixed obligations
Everything works until something changes.
And something always changes.
Flexibility Has a Real Return
Even though it’s not always visible, flexibility provides value.
It allows you to:
- Avoid high-cost borrowing in emergencies
- Take advantage of new opportunities
- Adjust to market conditions
- Make decisions without pressure
In uncertain environments, flexibility can outperform optimization.
Not in theory but in outcomes.
Finding the Balance
The goal isn’t to ignore optimization.
It’s to balance it with resilience.
That might mean:
- Keeping a larger emergency fund than strictly “necessary”
- Paying down debt aggressively but not exclusively
- Avoiding strategies that eliminate liquidity entirely
- Accepting slightly higher costs in exchange for optionality
This isn’t inefficiency.
It’s strategic positioning.
When Optimization Makes Sense
Aggressive optimization works best when:
- Income is stable and predictable
- Emergency savings are fully funded
- There’s low risk of near term disruption
- Flexibility has already been built
In these cases, pushing for efficiency can accelerate long term progress.
When Flexibility Should Take Priority
Flexibility becomes more valuable when:
- Income is variable
- Economic conditions are uncertain
- Major life changes are possible
- Existing debt already creates pressure
In these situations, preserving optionality can prevent larger setbacks.
The Bigger Picture
Personal finance isn’t just about minimizing cost.
It’s about managing risk over time.
Debt optimization improves efficiency.
Flexibility improves resilience.
The most effective strategies recognize that both matter.
The “best” financial move isn’t always the one that saves the most money on paper.
It’s the one that holds up under real world conditions.
Because a plan that works perfectly in theory but breaks under stress isn’t optimal at all.
And sometimes, the smartest move isn’t squeezing every dollar of efficiency…
It’s leaving yourself room to breathe.

